COMMERCIAL AVIATION
Analysis of the annual reports of Boeing, Airbus and IATA.
In recent decades, commercial aviation growth has undergone an extraordinary renewal. Operational efficiency has been optimized, airline business models have been redefined, and the transition toward more sustainable fleets has accelerated.
This process of transformation and expansion, combined with growing global demand, presents an unprecedented horizon of opportunities.
In this comprehensive analysis, we break down the future outlook for commercial aviation over the next two decades, based on the latest reports published by the two industry giants:
Explore the key trends: from the demand for new aviation professionals and aircraft to projected growth across every geographic region, including new routes.

According to the latest industry analyses, the outlook for 2026 confirms fully consolidated air travel demand on a global scale.
Data shows that global passenger volume will reach 5 billion passengers during 2026 (Source: Boeing CMO, p. 5), marking continuous traffic growth within a new phase of operational stability (Source: Airbus GMF, p. 4).
Both aerospace manufacturers agree that the growth trajectory is solid and estimate that world air traffic will double over the next 20 years (Source: Boeing CMO, p. 3, 7 / Airbus GMF, p. 12, 33), reaffirming the irreplaceable role of air transport in the global economy.
Key macroeconomic forecasts include:
Airbus forecasts a Compound Annual Growth Rate (CAGR) of 3.9% annually for the 2026–2045 period (Source: Airbus GMF, p. 12, 38), while Boeing projects an average growth rate of 4.0% annually (Source: Boeing CMO, p. 4, 7).
Aviation remains an indispensable economic engine, directly contributing 3.9% of global GDP (Source: Airbus GMF, p. 5). Furthermore, this expansion will be supported by an average global GDP growth of 2.6% annually according to Airbus (Source: Airbus GMF, p. 8) and 2.5% annually according to Boeing (Source: Boeing CMO, p. 4).

This data is further confirmed by the latest IATA Annual Economic Report (2026), which validates not only the consolidated recovery past pre-pandemic levels but also the transition into a more stable and mature growth phase following the initial rebound.
For 2026, IATA projections point to net industry profits of $23 billion for global airlines (Source: IATA Outlook for the Air Transport Industry / Boeing CMO Presentation 2026, p. 4), influenced by temporary headwinds such as a 70% increase in jet fuel costs.
Following a real traffic increase of 5.3% in 2025 (Source: Boeing CMO, p. 9), passenger traffic (RPK) growth will experience a slight moderation in 2026 with a projected annual rate of 2.3%. It is expected to rebound between 6% and 7% in 2027 before converging toward its historical long-term average.

This exponential growth is supported by several strategic pillars identified by Boeing and Airbus:
The primary driver is economic development and urbanization in emerging markets. The top 20 emerging economies are projected to add more than 500 million additional households earning over $20,000 annually by 2045 (Source: Boeing CMO, p. 6).
Globally, the population belonging to the middle and upper classes will grow by 1.7 billion people, reaching 6 billion by 2045 (Source: Airbus GMF, p. 8).
Both operational needs and environmental regulations drive fleet replacement. New-generation aircraft offer 20% to 25% reductions in fuel consumption and CO2 emissions per seat (Source: Airbus GMF, p. 37).
As a result, approximately 50% of Boeing’s new deliveries (21,475 aircraft) (Source: Boeing CMO, p. 6, 8) and 47% of Airbus’s deliveries (19,820 aircraft) (Source: Airbus GMF, p. 33, 38) will be dedicated directly to replacing older, less efficient units.
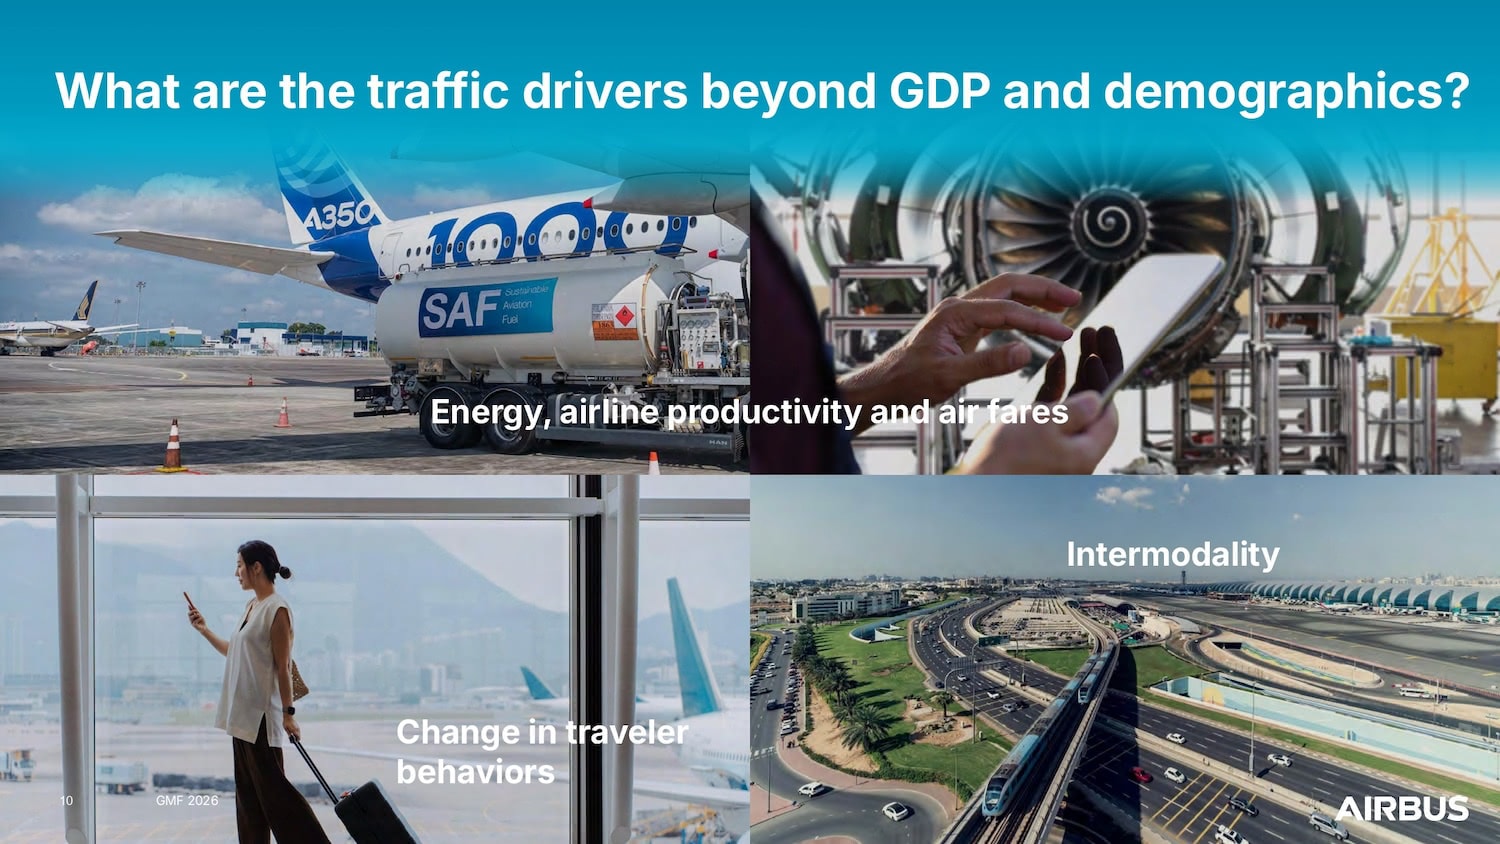
The expansion of Low-Cost Carriers (LCCs), whose fleet will grow at a rate of 3.9% annually according to Boeing (Source: Boeing CMO, p. 8), continues to democratize air travel.
Over the past decade, inflation-adjusted average airfares have dropped by 25%, and 5,500 new direct routes have been established (Source: Boeing CMO, p. 5, 6). In fact, 55% of city pairs operated in 2025 represent new routes created over the last 20 years (Source: Airbus GMF, p. 16).

The massive growth of the fleet translates directly into a historic demand for skilled professionals. The industry will require 2.4 million new personnel by 2045 (Source: Boeing CMO, Services Forecast), which breaks down into:
For this reason, being an airline pilot will always be a very good career opportunity; regardless of the natural cycles of economic growth and lethargy, commercial aviation is the engine that moves our world.
But not only commercial pilots are needed, but also flight attendants, so if you think it could be the right career for you, here are the requirements to become a flight attendant.


One Air, three times awarded as the Best Flight School in Spain.
Following post-pandemic recovery and expansion, the sector has broken historical records, with global passenger volume projected to exceed 5 billion passengers in 2026 (Source: Boeing CMO, p. 5). This is 500 million more travelers than in 2019 (Source: Boeing CMO, p. 5).
This record figure demonstrates the irreplaceable role and resilience of aviation in global connectivity. This dynamism is intrinsically tied to economic development and international tourism.
Aviation consolidates its role as the primary facilitator of international travel, being the transport mode chosen by 58% of all international tourists worldwide (Source: Airbus GMF, p. 5).

A direct consequence of air traffic growth is the necessity to expand and modernize the global aircraft fleet.
Projections from both manufacturers indicate that the worldwide in-service fleet will nearly double over the next two decades. Meeting this demand requires an unprecedented production volume:

These massive deliveries serve a dual strategic purpose: approximately half will replace older, less efficient aircraft; while the remaining half will drive net fleet growth.
Analyzing demand by aircraft category confirms the absolute dominance of single-aisle (narrow-body) aircraft due to their versatility on short- and medium-haul networks.

While mature markets like North America and Europe will focus on fleet replacement and operational efficiency, emerging economies in Asia, the Middle East, Latin America, and Africa will be the true engines of air traffic expansion, accounting for 55% of all new aircraft demand (Source: Boeing CMO, p. 8).
In fact, Asia will decisively lead global demand, absorbing over 19,000 new passenger aircraft deliveries over the next 20 years (Source: Airbus GMF, p. 34).
Below is the detailed breakdown by major geographic region for the 2026–2045 period.

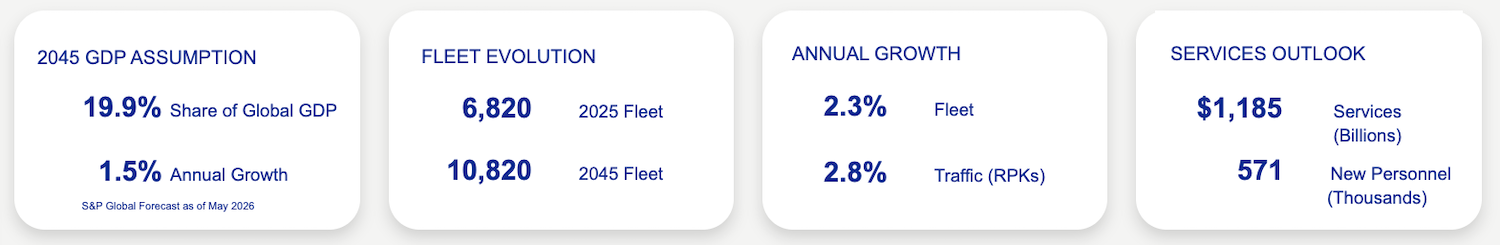
If there is one factor defining commercial aviation in Eurasia, it is the dominance and continuous expansion of Low-Cost Carriers (LCCs). This business model is no longer a niche, but the primary force driving intra-European traffic and redefining the rules of the game.
Low-cost airlines already control more than 50% of short- and medium-haul traffic in Europe, and their market share continues to grow. Their aggressive pricing strategy and operational efficiency have made flying more accessible than ever, constantly stimulating demand.

But the moment has arrived when the LCC model is breaking through its own boundaries.
Thus, airlines like Norse Atlantic (inheriting the spirit of Norwegian) or IAG’s LEVEL, alongside low-cost subsidiaries of major legacy groups such as Eurowings (Lufthansa) or Transavia (Air France-KLM), are applying low-cost principles to transatlantic routes.
This has introduced a new level of competition to long-haul flying, forcing traditional carriers to become more competitive.
This dynamic explains why the vast majority of new aircraft delivered to the region will be single-aisle: 6,920 units according to Boeing (Source: Boeing CMO, p. 4, 15, 16) and 6,690 according to Airbus (Source: Airbus GMF, p. 34).
These models are the perfect tool for the high-frequency, low-cost strategy of LCCs.
The second major driver of transformation in the Eurasian market is sustainability.
The region boasts the strictest environmental regulatory framework in the world, with mandates such as the European Union’s ‘Fit for 55’ requiring a drastic reduction in emissions.
This compels airlines to accelerate fleet renewal. In Eurasia, 53.4% of Boeing’s new deliveries (4,590 aircraft) will be dedicated exclusively to replacing older, less efficient aircraft (Source: Boeing CMO, p. 16).

The introduction of models like the Airbus A320neo or the Boeing 737 MAX, which offer fuel and CO2 reductions of up to 25%, is not just a regulatory necessity, but a competitive advantage.
Lower fuel consumption directly translates into lower operating costs—an indispensable factor in such a price-sensitive market.
Furthermore, this fleet volume will require training 571,000 new aviation professionals in Eurasia by 2045 (153,000 commercial pilots, 249,000 cabin crew members, and 169,000 MRO technicians) (Source: Boeing CMO, Services Forecast).
In conclusion, the future of aviation in Eurasia will be less about explosive growth and more about intelligent evolution.
Efficiency, sustainability, and the ability to compete in an environment dominated by the low-cost model will be the keys to success for airlines operating in this dynamic and demanding region.

The business model of major Gulf carriers (such as Emirates, Qatar Airways, and Etihad) is built around utilizing their airports as mega-hubs.
These connecting hubs are designed to minimize transit times and maximize efficiency, allowing passengers to travel between virtually any pair of cities worldwide with a single, seamless layover.

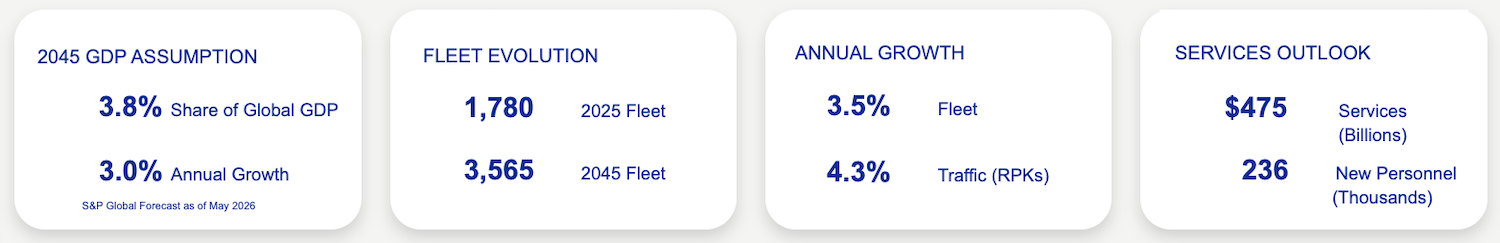
This operational model completely defines the region’s fleet demand. Unlike any other market where single-aisle aircraft dominate, widebody aircraft take center stage in the Middle East, accounting for more than 50% of deliveries (Source: Boeing CMO, p. 20 / Airbus GMF, p. 34).
Forecasts for the Middle East reflect maturity and specialization in long-haul flying:

This significant operational expansion will require the training of 236,000 new aviation professionals in the Middle East by 2045 (67,000 commercial pilots, 104,000 cabin crew members, and 65,000 MRO technicians) (Source: Boeing CMO, Services Forecast).
In conclusion, the Middle East will not only maintain but reinforce its position as an indispensable pillar of global aviation.
Its ‘super-connector’ strategy, combined with its transformation into a premier tourism destination, guarantees strong, sustained demand—especially for twin-aisle aircraft, the undisputed queens of intercontinental routes.

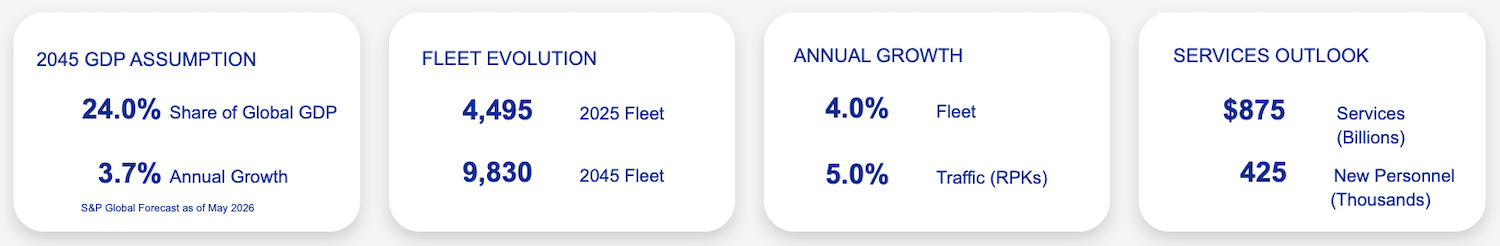
To sustain this expansion, fleet and personnel requirements are monumental:

Regarding qualified personnel demand, the figures illustrate the magnitude of the operational challenge. China will require 425,000 new aviation professionals by 2045 (Source: Boeing CMO, Services Forecast), including:
This demand reflects not only rapid expansion but also the need to operate one of the youngest and most modern fleets in the world, with an average aircraft age significantly lower than that of European or North American markets.

The primary engine of Chinese aviation growth is its domestic market.
Driven by an expanding middle class, vast geography, and a high-speed rail network that feeds air traffic into major hubs rather than competing with it, China’s domestic market is set to make history.
Ultimately, China will not only lead growth in volume, but will also establish new benchmarks for infrastructure, fleet modernity, and talent demand, consolidating its role as the 21st-century center of gravity for commercial aviation.

Latin America positions itself as one of the most dynamic regions for commercial aviation over the next two decades.
Despite economic volatility and infrastructure challenges, its potential is immense, driven by a unique combination of geographical necessity and the explosion of the low-cost model.
Forecasts reflect this optimism:

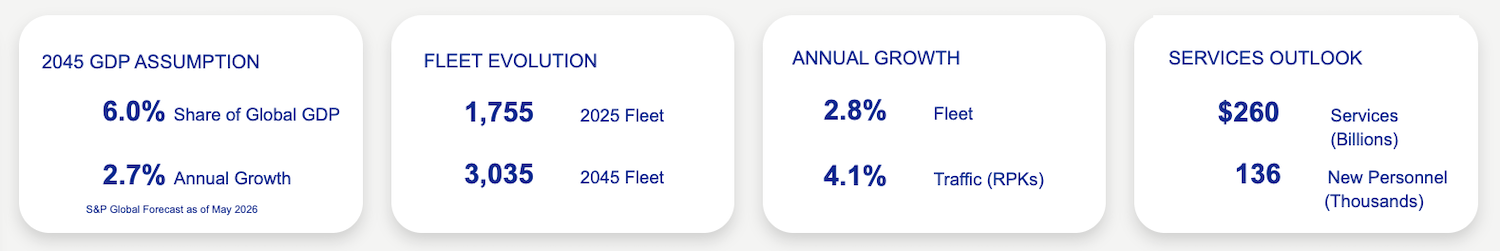
The nature of the Latin American market, with its heavy emphasis on short- and medium-haul routes, completely shapes fleet demand for the coming decades.
Regarding total delivery demand for the 2026–2045 period, manufacturers forecast:

Among these new deliveries, single-aisle aircraft dominance is absolute: they will represent 90% according to Boeing (2,160 aircraft)—the highest proportion of any region in the world (Source: Boeing CMO, p. 18)—and 93% according to Airbus (2,520 aircraft) (Source: Airbus GMF, p. 34).
Models such as the Airbus A320neo and the Boeing 737 MAX serve as the perfect tools for low-cost carriers to connect the continent’s extensive city network efficiently.
Demand for widebody aircraft will be more modest, with 230 units according to Boeing (10%) (Source: Boeing CMO, p. 18) and 200 according to Airbus (7%) (Source: Airbus GMF, p. 34), focused on long-haul routes to North America and Europe.
The most disruptive and powerful driver of recent growth has been the consolidation and expansion of low-cost carriers.
Airlines like Volaris, Viva Aerobus, JetSMART, and SKY Airline have democratized access to air travel for millions of people who previously relied on long-distance buses.
This model has stimulated new and growing demand, particularly in key domestic markets such as Mexico, Brazil, and Colombia. In fact, Brazil’s domestic market will rank among the top 20 global air traffic flows by 2045 with 3.6% annual growth (Source: Airbus GMF, p. 13, 14).
The result is a far more competitive market offering more routes, higher frequencies, and lower fares, which in turn fuels a virtuous cycle of traffic growth.

To sustain this expansion, Latin America will require 136,000 new aviation professionals by 2045 (38,000 commercial pilots, 56,000 cabin crew members, and 42,000 MRO technicians) (Source: Boeing CMO, Services Forecast).
In conclusion, while significant challenges persist—such as the need to modernize airport infrastructure and manage economic volatility—the underlying fundamentals of the Latin American air travel market are exceptionally strong.
The combination of real geographical necessity and the operational efficiency of the low-cost model ensures that the region will remain a key focus of growth and opportunity for global aviation.

The central challenge in North America is replacing thousands of aircraft approaching the end of their operational lifespan.
The need to reduce operating costs, meet environmental targets, and cater to premium international traffic—which has grown nearly 50% since 2019—is driving an unprecedented wave of fleet replacement (Source: Boeing CMO, p. 21, 22).
By the numbers, for the 2026–2045 period, manufacturers forecast:

This means that in the North American market, for every ten new aircraft delivered by manufacturers, more than seven will be used to retire an older plane.
This will drastically lower the average age of the regional fleet (which for single-aisle aircraft currently stands at 16 years, 4 years above the global average) (Source: Boeing CMO, p. 22).
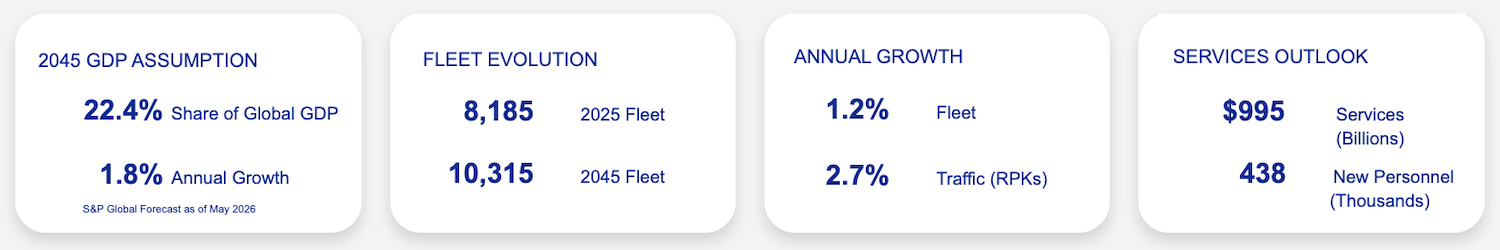
The total active fleet will expand from 8,185 in 2025 to 10,315 aircraft in 2045 according to Boeing (Source: Boeing CMO, p. 4, 21, 22) and from 5,570 to 7,350 according to Airbus (Source: Airbus GMF, ‘Fleet in Service’).
The geography and structure of the US market dictate that single-aisle aircraft will be the most in-demand type.
The vast network of domestic and transborder routes (with Mexico and Canada) accounts for roughly three-quarters of all air traffic in the region (Source: Boeing CMO, p. 21).

Furthermore, this immense operational market will require the induction of 438,000 new aviation professionals in North America by 2045 (122,000 commercial pilots, 191,000 cabin crew members, and 125,000 MRO technicians) (Source: Boeing CMO, Services Forecast).
In summary, North America will not easily yield its position as an industry titan to China. Its leadership over the coming decades will be anchored in transformation—investing billions to operate the most modern, efficient fleet on the planet and ensuring the long-term sustainability of its vital commercial aviation sector.

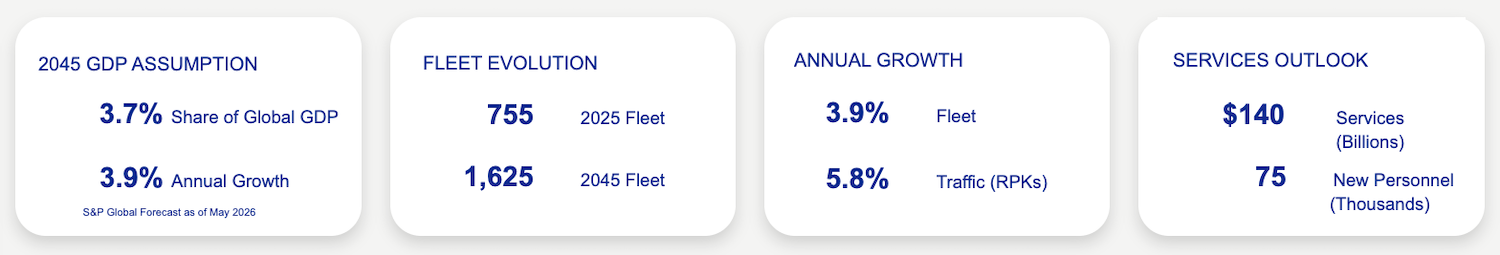
This explosive traffic growth will generate a massive demand for new aircraft.
Africa’s commercial fleet, currently one of the smallest and oldest in the world, must more than double to meet future demand.
The commercial fleet in Africa will expand from 755 aircraft in 2025 to 1,625 aircraft by 2045 according to Boeing (Source: Boeing CMO, p. 4, 11, 12) and from 650 to 1,920 passenger aircraft according to Airbus (Source: Airbus GMF, ‘Fleet in Service’).
To achieve this, manufacturers project the following new aircraft deliveries for the 2026–2045 period:

The bulk of demand will concentrate on single-aisle aircraft to serve domestic and intra-regional routes, which will experience the greatest expansion.
Demand for widebody aircraft will also be key to connecting Africa with its primary trading partners in Europe and the Middle East, as well as supporting its growing tourism and business hubs.
Optimism in these forecasts is supported by three key pillars:

Despite huge potential, challenges remain. African airlines face higher operating costs compared to other regions, regulatory fragmentation, and the need for airport infrastructure modernisation.
However, the opportunity is immense. Low-cost carrier (LCC) penetration in Africa remains well below the global average, representing a market segment with giant growth potential.
The arrival of more efficient, new-generation aircraft with lower seat-mile costs will allow both LCCs and network carriers to expand their networks profitably.
Furthermore, this fleet expansion will create significant employment opportunities, requiring 75,000 new aviation professionals by 2045 (22,000 commercial pilots, 28,000 cabin crew members, and 25,000 MRO technicians) (Source: Boeing CMO, Services Forecast).
In conclusion, analyses from Boeing and Airbus are unanimous: Africa stands at the threshold of an aviation revolution. Overcoming operational challenges and accelerating market integration through initiatives like SAATM will unlock the full potential of a continent destined to become a major player on the 21st-century global aviation map.


The focus is not on a massive increase in the sheer number of aircraft, but rather on replacing long-haul fleets with latest-generation models.
Specifically, 68% of all new deliveries to the region (1,080 aircraft) will be dedicated exclusively to replacing older units (Source: Boeing CMO, p. 24).
Airlines in the region will look to replace their older widebody aircraft with ultra-efficient models such as the Boeing 787 and the Airbus A350.
These aircraft not only drastically reduce fuel consumption, but also allow airlines to operate intercontinental routes more profitably, strengthening the position of their hubs.
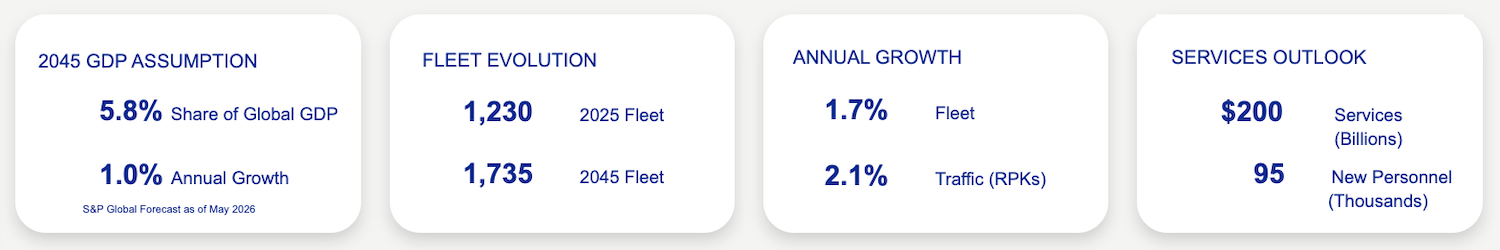
For the 2026–2045 period, forecasts project a total demand for 1,585 new aircraft in Northeast Asia (Source: Boeing CMO, p. 4, 24). The active in-service commercial fleet will expand from 1,230 in 2025 to 1,735 aircraft in 2045 (Source: Boeing CMO, p. 23, 24).

The delivery structure by aircraft type reflects this high degree of specialization (Source: Boeing CMO, p. 23, 24):
The future of the airline market in this region is marked by two unique factors that moderate its growth—fixing passenger traffic (RPK) growth at 2.1% annually (Source: Boeing CMO, p. 4, 23)—while simultaneously driving innovation:
To operate this cutting-edge fleet, Northeast Asia will require the training of 95,000 new aviation professionals by 2045 (24,000 commercial pilots, 43,000 cabin crew members, and 28,000 MRO technicians) (Source: Boeing CMO, Services Forecast).
In conclusion, Northeast Asia will consolidate its position as a high-value market where technology, fleet efficiency, and service quality will be the key drivers of success.
It will serve as a showcase for the world’s most advanced aircraft, operating in one of the planet’s most competitive and demanding environments.


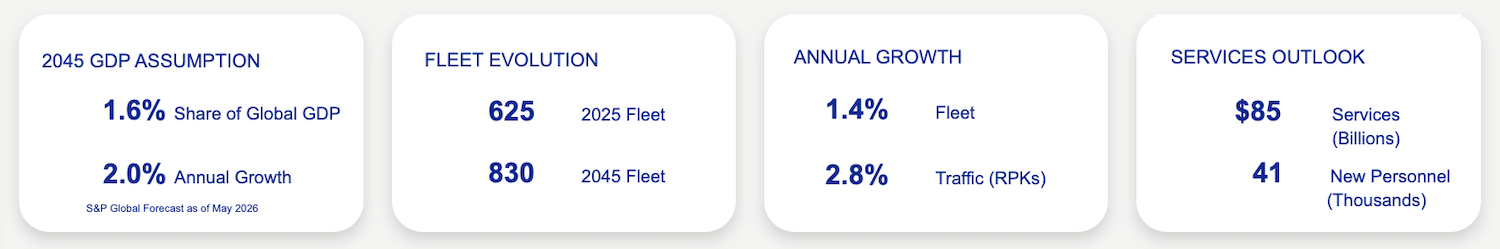
The unique nature of Oceania is perfectly reflected in its fleet demand for the next two decades, which will swing between two extremes:
In terms of total demand for the 2026–2045 period, the region will require 765 new aircraft (Source: Boeing CMO, p. 4, 26) to renew its fleet and accommodate growth, expanding the active commercial fleet from 625 units in 2025 to 830 aircraft in 2045 (Source: Boeing CMO, p. 4, 25, 26).

On one hand, the vast majority of these deliveries (74%) will be single-aisle aircraft (Source: Boeing CMO, p. 25, 26) to serve the robust Australian domestic market and high-frequency regional routes, such as those connecting Australia with New Zealand (Trans-Tasman routes) and the Pacific Islands.
These aircraft currently provide 40% of seat capacity between the South Pacific and Asia (Source: Boeing CMO, p. 25). Next-generation models like the Airbus A321XLR and the Boeing 737 MAX family are essential.
On the other hand, although smaller in share (24%), widebody aircraft demand holds immense strategic value (Source: Boeing CMO, p. 26).
This twin-aisle share is significantly higher than the global average (18%), driven by the fact that 6 of the 10 longest commercial flights on the planet connect Oceania with other regions (Source: Boeing CMO, p. 26).
For Oceania, flying is vital. It is essential both for connecting population centers across Australia separated by thousands of kilometers (a Sydney to Perth flight is longer than Madrid to Moscow) and for linking the region with trading partners and tourist destinations across Asia, the Americas, and Europe.
This necessity has driven Oceanian airlines to aggressively accelerate fleet replacement: more than 7 out of 10 in-service aircraft (73.2% / 560 units) will be replaced by newer, more efficient models (Source: Boeing CMO, p. 26)—a replacement rate well above the global average.
Furthermore, this momentum has led airlines like Qantas to pioneer ultra-long-range aviation. The most striking and fascinating example of this trend is ‘Project Sunrise’. This ambitious plan aims to operate direct, non-stop commercial flights from Sydney and Melbourne to destinations as distant as London and New York, with flight times around 20 hours.
To achieve this feat, Qantas has ordered a fleet of specially modified Airbus A350-1000s, featuring additional fuel tanks and a cabin interior designed for maximum comfort on extreme-duration journeys (Source: Airbus GMF, p. 28, 29). This project represents the new frontier of commercial aviation.
In conclusion, Oceania will remain a benchmark market in the industry. Although its growth in absolute volume will be modest, its role as a catalyst for innovation in ultra-long-distance flights makes it a key player shaping the future of global connectivity.


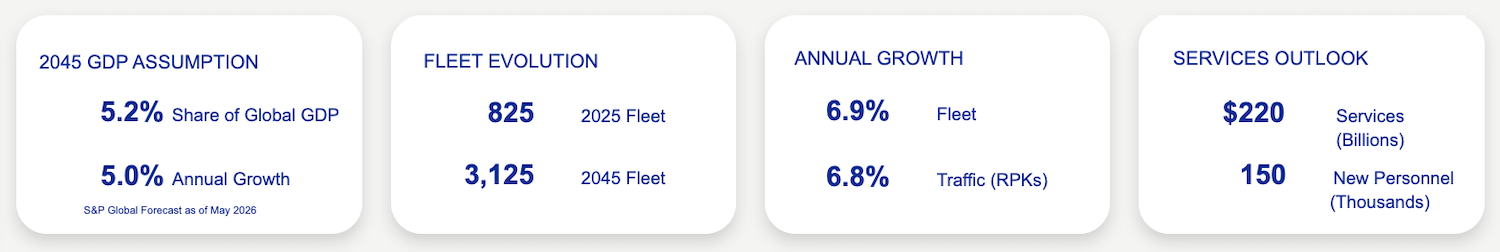
Future fleet structure reflects the overwhelmingly domestic and regional character of the market. For total new aircraft delivery demand between 2026 and 2045, manufacturers forecast:
The vast majority of these planes—87% according to Boeing and 91% according to Airbus—will be single-aisle models to feed insatiable domestic route demand.

At the same time, growing demand for widebody aircraft is expected: 390 units according to Boeing (11%) (Source: Boeing CMO, p. 28) and 300 according to Airbus (9%) (Source: Airbus GMF, p. 34) to support the international expansion of Indian airlines, whose long-haul fleet will nearly quadruple to compete directly on major intercontinental routes.
The most tangible proof of these forecasts is the recent record-breaking aircraft orders placed by Indian carriers.
Airlines such as Air India and IndiGo have placed firm orders for hundreds of aircraft with Airbus and Boeing, in deals valued at tens of billions of dollars. These ‘mega-orders’ are not a gamble, but a necessity to serve the expected surge in demand.
Indeed, the analogy fits the region’s dynamism perfectly, which is explained by a ‘perfect storm’ of driving factors:
To support this historic expansion, South Asia will require the addition of 150,000 new aviation professionals by 2045 (48,000 commercial pilots, 54,000 cabin crew members, and 48,000 MRO technicians) (Source: Boeing CMO, Services Forecast).
In conclusion, South Asia—led by India—is not only the fastest-growing market, but is on a clear trajectory to become one of the top three commercial aviation markets in the world, trailing only China and North America.


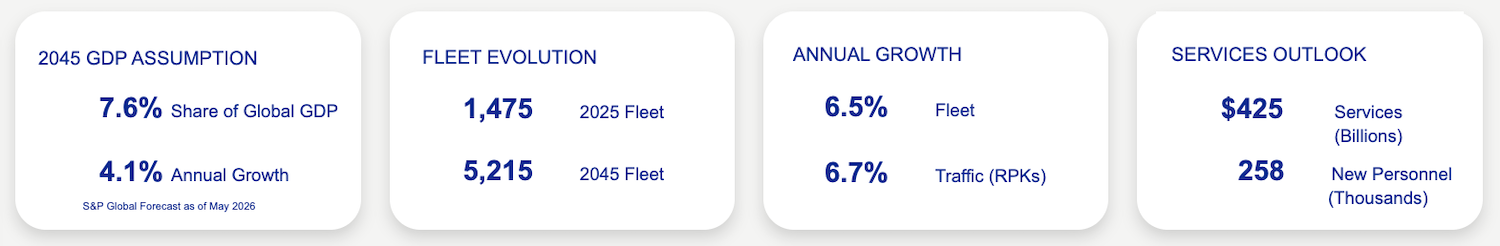
The future of Southeast Asia will be written with epic growth figures.
On one hand, the region will absorb 4,985 new aircraft for the 2026–2045 period according to Boeing (Source: Boeing CMO, p. 4, 30), while for the broader Asia-Pacific macro-region (excluding China and India), Airbus projects 6,880 new passenger aircraft (Source: Airbus GMF, p. 34).
As noted, the fleet will be predominantly single-aisle to serve the dense route network connecting thousands of cities across the region.
On the other hand, countries like Vietnam are leading the expansion with strong performance in their export and tech sectors, driving the construction and expansion of major airport infrastructure to manage rising traffic (Source: Boeing CMO, p. 29).

Furthermore, airlines such as AirAsia, Lion Air, and VietJet have made flying accessible to a dense, young population increasingly integrated into the digital economy.
This fierce competition among LCCs decisively shapes fleet demand: their single-aisle fleets will grow at a rate near 7.5% annually through 2045 (Source: Boeing CMO, p. 29).
Consequently, Boeing forecasts indicate that out of the 4,985 new aircraft the region will require, 4,080 units (~82%) will be single-aisle models (Source: Boeing CMO, p. 30)—the quintessential tool of the low-cost model. Meanwhile, 855 units (~17%) will be widebody aircraft to accommodate long-haul traffic growth (Source: Boeing CMO, p. 30).
For nations composed of thousands of islands, such as Indonesia and the Philippines, aviation is not an alternative—it is the primary transport artery. It connects people, enables trade, and unifies the nation.
This reliance on air travel for basic connectivity creates an extraordinarily solid and resilient domestic demand base.
Additionally, the region is a global tourism magnet, adding a robust layer of international demand that links its famous destinations with the rest of the world, primarily through major hubs like Singapore, Bangkok, and Kuala Lumpur.
In conclusion, Southeast Asia is and will remain an attractive, highly competitive playing field.
The combination of fundamental geographical necessity, the proven success of the LCC model, and its tourist appeal guarantees that the region will not only grow, but will be one of the key markets defining the future of global commercial aviation.


Following this comprehensive analysis of Boeing and Airbus forecasts for the 2026–2045 period, the conclusion is undeniable: commercial aviation is entering two decades of historic expansion. The requirement to deliver nearly 43,000 new aircraft is tangible proof of a thriving global industry.
For anyone dreaming of an aviation career, this is the most critical takeaway: every single one of those thousands of new aircraft requires qualified flight crews to operate.
Projections indicate a demand for 2.4 million new professionals over the next 20 years, including approximately 674,000 commercial pilots, 1,023,000 cabin crew members (flight attendants), and 728,000 maintenance technicians (MRO).
This translates into an unprecedented career opportunity offering long-term stability and growth that few other sectors can match. The question is no longer whether jobs will be available, but rather who will be the best-prepared candidates to secure the top positions.